States We Lend In
Our loan officers are ready and waiting to help you apply for your home loan.

Before you schedule home tours or attend open houses, there is an important first step that can impact your home buying experience: getting pre-approved for a mortgage.
Mortgage pre-approval involves an official review of your income, credit, and assets by a mortgage lender.
This process provides a more informed estimate of the loan amount you may qualify for based on the financial information reviewed by the lender, helps you spot and resolve potential credit or paperwork issues early, and ensures you make the right decision.
|
Quick Answer: Should You Get Pre-Approved Before Finding a Home?
Yes, absolutely. Getting pre-approved before actively house hunting can help you establish a realistic price range, understand potential financing options, and be better prepared to make an offer when you find the right home. It’s easy to start browsing online listings or going to open houses. But getting pre-approved first saves you time and keeps you from getting hurt. Ultimately, mortgage pre-approval does these things:
|
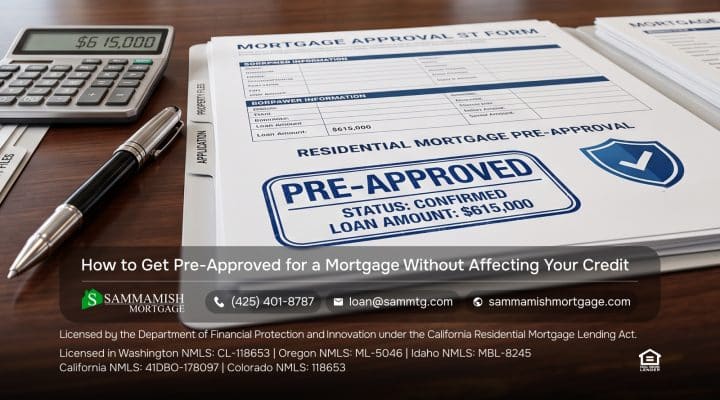
Mortgage pre-approval is an official green light from a bank.
It’s not a guess. To get a home loan pre-approval, the bank checks your actual financial numbers.
During the mortgage pre-approval process, a lender checks your job, pay stubs, bank accounts, debts, and credit score.
Online home calculators give quick estimates, but they do not check your paperwork.
A pre-approval letter for home buying is an official note saying the bank has verified your info and is ready to loan a certain amount of money.
| Pro Tip: Use our mortgage calculator online to estimate your mortgage payments before signing on the dotted line. |
Here’s why getting pre-approved before buying a house is the right first step.
Loving a $500,000 house when the bank will only lend you $400,000, for example, is painful. Pre-approval keeps your search realistic.
|
Example: Home prices and property tax rates vary dramatically across major Western markets, from high-cost metros like Seattle, Los Angeles, and Denver to rapidly growing regions like Portland and Boise.
Getting pre-approved ensures your target price matches the specific location where you plan to buy. |
A home’s price tag is only part of what you pay. Taxes, home insurance, and interest rates change your monthly bill. Pre-approval provides a clear monthly dollar number.
If there’s a mistake on your credit report, finding it early gives you time to fix it before making an offer on a property.
Different home loans have different down payment rules. Pre-approval allows you time to pick the right option for your situation.
When you find the right house, you have to move quickly.
Being pre-approved before making an offer gives you a big advantage over other buyers.
If you find your dream house before getting pre-approved, you could run into big problems:
Mortgage pre-approval evaluates a borrower’s income, debts, assets, credit profile, down payment, estimated housing expenses, and loan program to determine a potential loan amount.
A mortgage pre-approval can help establish the price range you may qualify for, but the maximum amount a lender approves doesn’t necessarily have to become your home-buying budget.
Buyers should also consider their monthly expenses, savings goals, emergency reserves, and preferred monthly housing payment.
When estimating your full budget, account for:
To give you a mortgage pre-approval before finding a home, the bank checks five basic items:
How long a home loan pre-approval takes depends on how fast you submit your paperwork and the lender’s specific verification guidelines.
Having your documents ready makes things move fast.
Depending on your loan program and financial situation, a lender may request the following:
Mortgage pre-approval vs pre-qualification may sound alike, but they are very different:
| Feature | Pre-Qualification | Pre-Approval |
| Purpose | Early afforablility estimate | More detailed mortgage evaluation |
| Accuracy | A quick estimate | An official, checked number |
| Documents | May ne limited (you just state numbers) | Lender checks pay stubs and taxes |
| Credit Check | Soft check or none (depends on the lender) | Real credit check by the bank |
| Loan Amount | Preliminary estimate | Conditional amount based on reviewed information |
| Seller Trust | Low | High |
| When to Use | Early planning stages | Active home shopping and making offers |
| Final Loan Approval | No | No |
Pre-approval and pre-underwriting both assess your mortgage readiness, but they differ in how thoroughly your finances are reviewed.
| Feature | Pre-Approval | Pre-Underwriting |
| Financial information reviewed | More detailed than pre-qualification | More comprehensive |
| Documentation reviewed | Yes | Yes |
| Credit Reviewed | Generall yes | Yes |
| Underwriter Review | May vary by lender/process | Yes |
| Useful before home shopping | Yes | Yes |
| Final loan approval | No | No |
Note: Terminology and verification processes can vary by lender.
For home buyers seeking an even stronger position in competitive markets, programs like our Diamond Homebuyer Program take pre-approval a step further by fully underwriting your file prior to finding a property.
No. A mortgage pre-approval is not a final loan approval or guarantee of financing.
Final approval generally depends on the property, appraisal, title, updated borrower documentation, underwriting requirements, and whether the borrower’s financial circumstances remain acceptable through closing.
Changes such as these can affect financing:
Be sure to steer clear of the following after getting pre-approved:
Before making a major financial change between pre-approval and closing, talk with your lender about whether it could affect your mortgage qualification.
Once you are pre-approved, you’ll generally follow these steps:
For a detailed look at navigating these next steps, read our guide on What Actually Happens After You Get Pre-Approved?.
Get your timing right to keep the process smooth:
Getting pre-approved for a mortgage before house hunting means you’re a vetted, competitive buyer.
A lender’s formal assessment of your income, credit, and assets sets an accurate budget and eliminates financing surprises down the road. Sellers prioritize offers supported by official pre-approval letters. Secure your pre-approval today so you’re ready to make a quick, strong offer as soon as your dream home hits the market.
Do you want to get pre‑approved for a mortgage before you start the hunt for a new home? If so, Sammamish Mortgage can help. Since 1992, we’ve helped borrowers across Washington, Idaho, Colorado, Oregon, and California. We provide many mortgage programs, including our Diamond Homebuyer Program, Cash Buyer Program, and Bridge Loans. Visit our website to get an instant rate quote. Contact us today!
Yes, getting pre-approved for a mortgage first defines your exact budget and strengthens your buying power.
No, pre-approval is not a guarantee of final financing. Final loan approval depends on the appraisal, title check, updated documentation, and your financial situation being stable until closing.
Avoid opening new credit accounts, taking on new debt, making major financed purchases, changing jobs, or moving money around without documentation prior to closing.
Yes, your pre-approval amount can change if your income, debts, credit score, down payment, or interest rates change before you secure a loan.
After pre-approval, you establish your price range, select a loan strategy, shop for homes, make an offer, provide property information to your lender, and proceed through underwriting, appraisal, and closing.
Apply early in your home shopping process so you have time to fix credit errors or collect documents.
Yes, you can browse listings online, but real estate agents typically want a pre-approval letter for private tours.
Apply 30 to 90 days before home shopping so you have time to fix credit errors or collect documents.
Your score may dip temporarily by a few points. But multiple mortgage checks within 45 days count as one.
Most lenders issue a pre-approval letter within 24 to 72 hours after receiving your complete financial documents.
Letters are typically valid for up to 90 days before requiring up-to-date pay stubs and bank statements.
You need 30 days of pay stubs, 2 years of W-2s and tax returns, 60 days of bank statements, and photo ID.
No, pre-qualification is an unverified guess, while pre-approval is an official check backed by document verification.
You can try, but sellers rarely accept offers with no pre-approval letter proving you can secure financing.
Yes, you can be denied if your job, income, or credit score changes before loan closing, or if property underwriting conditions are not met.
Not necessarily, because lenders evaluate pre-tax income rather than your personal everyday spending habits and savings goals.
Yes, self-employed buyers can get pre-approved before shopping for a home by providing 2 years of bank statements and tax returns.
Our loan officers are ready and waiting to help you apply for your home loan.
Learn more about the people behind Sammamish Mortgage
Whether you’re buying a home or ready to refinance, our professionals can help.
Mortgage Support — 24/7
No Obligation and transparency 24/7. Instantly compare live rates and costs from our network of lenders across the country. Real-time accurate rates and closing costs for a variety of loan programs custom to your specific situation.
Adjust the parameters based on what you want to track